India's insolvency regulator has published 9,531 liquidation auction notices since the IBC's early years. Read as a register rather than case by case, they show something case-by-case coverage rarely captures: exactly how much value a failed auction destroys, on a markdown schedule the regulations themselves set out in percentages.
Insolvency & Bankruptcy · IBC Liquidation · Corporate Distress
What a Failed Bankruptcy Auction Actually Costs, in India's Own Numbers
Revised
· v1.0.0 · what changed
India's Insolvency and Bankruptcy Board maintains a public, page-by-page list of every liquidation auction notice issued under the IBC — corporate debtor, reserve price, what's for sale, when the auction is. Individually, each one is a routine filing. Assembled into a single register of 9,531 notices, they show a mechanism that rarely gets discussed in percentage terms: a real, regulator-set markdown schedule for what happens when nobody bids.
A register nobody reads end to end
The notices sit at ibbi.gov.in, twenty to a page, roughly 481 pages deep. A full scrape run on 24 July 2026 captured 9,528 of 9,531 listed notices, with fields for the corporate debtor's name, notice and auction dates, the insolvency professional running the sale, the reserve price, and a free-text description of the assets on offer.
What gets marked down, and by how much
Until a February 2024 amendment tightened the rule, IBBI's Liquidation Process Regulations let a liquidator cut the reserve price by up to 25% after the first failed auction, and by up to a further 10% after each failed auction beyond that. That is not a vague industry habit — it is a specific, regulator-set percentage, and the register shows it applied almost exactly.
| Corporate debtor | Auction date | Reserve price | Change |
|---|---|---|---|
| Athena Chhattisgarh Power | 22 Dec 2021 | ₹1,503.08cr | — |
| Athena Chhattisgarh Power | 7 Jan 2022 | ₹1,127.31cr | -25.0% |
| Athena Chhattisgarh Power | 24 Jan 2022 | ₹1,014.58cr | -10.0% |
| Punj Lloyd | 10 Jul & 28 Aug 2023 | ₹1,061.00cr | — |
| Punj Lloyd | 13 Oct 2023 | ₹955.00cr | -10.0% |
Athena Chhattisgarh Power's three rounds inside five weeks are a near-exact textbook case: a 25.0% cut on the first re-listing, then a further 10.0% cut on the second — the maximum the old regulation allowed at each step. Punj Lloyd's register entries show the same 10% step on its final re-listing. Not every repeat listing in the register follows this pattern this cleanly: Ind-Barath Thermal Power's plant and land near Tuticorin and Karwar appear at three different reserve prices across mid-to-late 2023 that don't move in one direction, because each listing bundled a different combination of the sale's ten defined asset blocks rather than simply re-offering the same lot cheaper. The markdown ladder is real; it isn't the only thing driving repeat listings.
What's actually being sold
The free-text asset descriptions, however inconsistently worded, point in one clear direction: liquidation auctions are overwhelmingly a real-estate and physical-plant register, not a market for brands, patents or going-concern intangibles.
| Asset type (as described) | Notices |
|---|---|
| Land and Building | 157 |
| Land | 120 |
| Land & Building | 93 |
| Plant & Machinery (both spellings) | 147 |
| Open Plot | 32 |
| Inventory | 34 |
| Residential Flat | 23 |
Counts are for the exact free-text phrasing captured in the scrape; near-duplicate wordings for the same underlying asset type (for example "Land & Building" vs "Land and Building") were not merged beyond the two Plant & Machinery spellings shown, so the true totals for land- and building-type assets are almost certainly higher than any single row here suggests.
The long tail: Dunlop India, thirteen years and counting
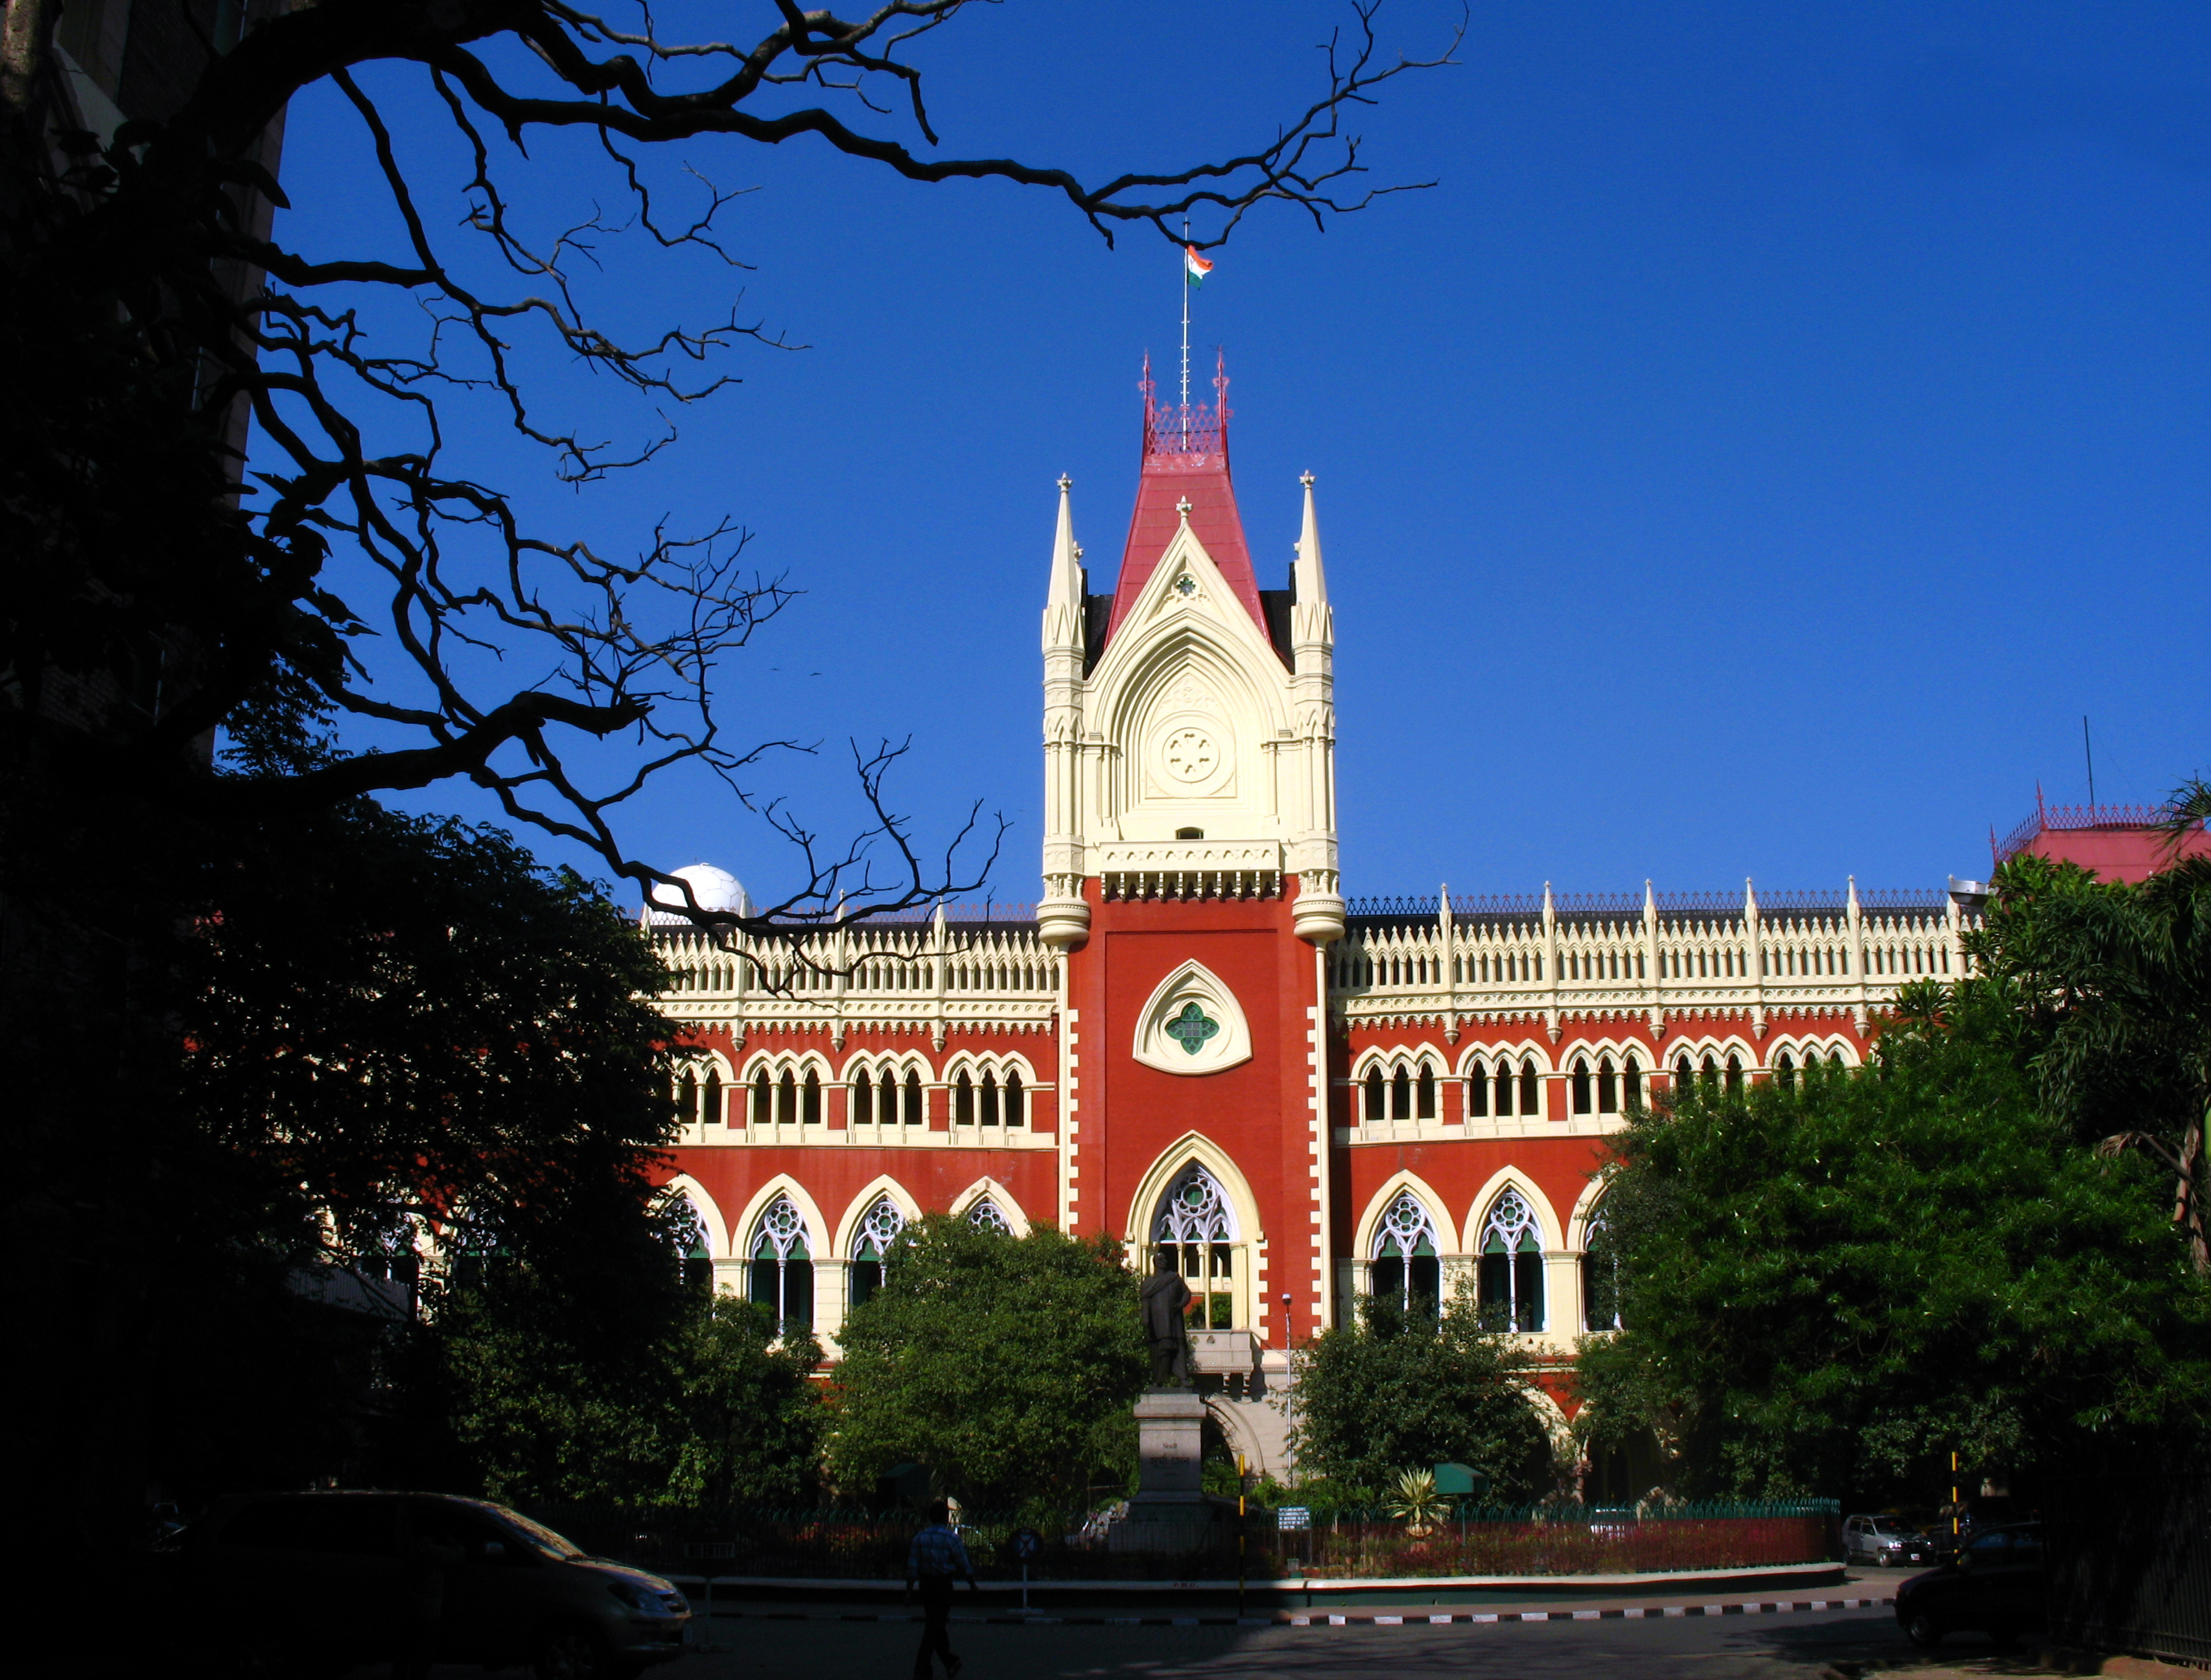
Most of the register is auctions that eventually clear, at some markdown. Dunlop India Ltd. — incorporated in 1929 as Dunlop Rubber Co. (India), later passing from the Chhabria (Jumbo) group to the Ruia group in 2005 — shows the other tail. Its Sahaganj (Hooghly, West Bengal) and Ambattur (Chennai) plants were suspended in 2011 and 2012; the Calcutta High Court ordered the company wound up on 31 January 2013, with an appeal dismissed that May. What has followed since is not a sale but litigation: a division-bench order the same year flagged an allegation that roughly ₹2,300 crore of the company's most valuable properties had been surreptitiously transferred while the case sat before the erstwhile Board for Industrial and Financial Reconstruction. One of those properties — a 50% share in "Kings Court," a five-storey, twelve-flat building on Chowringhee Road in Kolkata — is still contested: a Calcutta High Court judgment as recent as 17 March 2026 let an official-liquidator auction stand while giving one rival claimant the right to match the winning bid and another the liberty to separately sue for specific performance. Thirteen years after the winding-up order, the company's most valuable urban asset has still not finished changing hands.
The net read
A single register holds both stories at once. For most of the 9,531 notices, "liquidation" means a plant, a plot or a flat moving through a markdown ladder the regulator wrote down in percentages, clearing eventually at some discount to its first asking price. For a smaller number, it means a company that stopped operating over a decade ago, its most valuable land or buildings still working through the courts long after the corporate entity itself ceased to matter. The register counts every auction attempt; it does not, on its own, tell you which kind of case any single notice belongs to.
Sources: this ecosystem's own digital-twin-for-ipa research (layer 34, "stressed_assets," built 2026-09-14), specifically its live IBBI liquidation-auction-notice register (scraped from ibbi.gov.in/liquidation-auction-notices on 24 July 2026, 9,528 of 9,531 notices captured; reserve-price and auction-date figures for Athena Chhattisgarh Power, Punj Lloyd and Ind-Barath Thermal Power, and the asset-type-mix counts, are drawn directly from that scrape) and its worked case study on Dunlop India (sourced in turn to a Calcutta High Court division-bench order and a 17 March 2026 judgment on indiankanoon.org, not independently re-verified against the court record for this post). The pre- and post-February-2024 IBBI reserve-price markdown rules are per legal-industry coverage of the amendment (Lexology, TaxGuru) found via search.
- v1.0.0 — 15 September 2026 — first published.
About this article: Researched, written and edited by Umashankar Triplicane Dwarakanathan, with AI research assistance; every figure is meant to trace to the primary source cited. See the Editorial Policy for how sourcing, AI use and corrections work.
